Financing/Buy here, pay here

The bank said no. We might not.

In-house financing means we carry the loan ourselves. About half down, up to two years, at a higher rate than a bank. In return, we can approve people a bank won't.

Typical down payment~50%
Maximum term24 mo
APR18.99–24.99%
Prepayment penalty$0

Who it's for

Who it's for

Credit

A rough few years

Bankruptcy, a repo, medical collections, a thin file. A lender's software sees a score; we see a down payment and a job.

Income

Hard-to-document income

Self-employed, cash-heavy, seasonal or newly employed. If you can show us how you get paid, we can work with it.

The RV

Too old for a bank

Lenders cut off at a model year. A well-kept older trailer we've inspected and repaired can be a great buy that no bank will write.

Living in it

Full-timers

Many lenders won't finance an RV that's going to be a primary residence. Tell us up front — it isn't a problem here.

The terms

The terms

ItemIn-house financing
Down paymentTypically about 50%
TermUp to 24 months
Interest rate18.99% – 24.99% APR
Who qualifiesTotal monthly debt payments, including the new one, under 50% of your gross monthly income — the same debt-to-income test most lenders use
PaymentsMonthly — online, by phone or in person in Lincoln
Late payment10-day grace period, then a late charge of 10% of that month's payment
DecisionOne business day on a complete application
Early payoffNo prepayment penalty — pay it off any time
Credit reportingWe don't currently report in-house loans to the credit bureaus — paying on time won't raise your score, and a rough patch won't lower it
GPSFinanced units carry a GPS locator until the loan is paid off. It's disclosed in your contract and removed when you're done.
Why half down? RVs depreciate fastest in the first years of a loan. With half down you never owe more than it's worth — which protects you if life changes, and is the only reason we can skip the bank's credit box.
Trade-ins count. Equity in your current RV goes toward the down payment. Get your numbers first. What's my RV worth →
It costs more than a bank. If an outside lender will approve you, take them — the rate will be lower. We run every application past them first for exactly that reason.
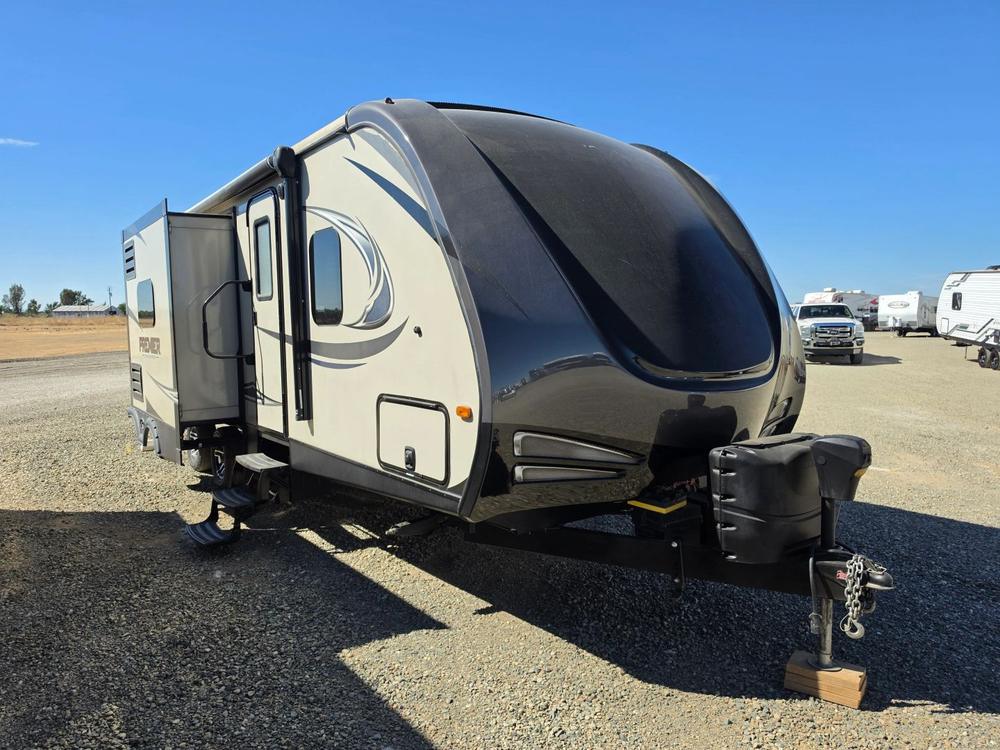
Same RV, same promises

What doesn't change

  • Inspected in our own bays before it's listed, with the report on the listing
  • Free two-hour orientation with a technician
  • RV Guard service contract available, same as any other sale
  • Service after the sale from the shop you're already making payments to

Questions

In-house financing FAQ

Do I fill out a different application?

No. Same application. We try outside lenders first, and if they pass, we look at it ourselves.

Can I put down less than half?

Sometimes — it depends on the RV, your income and your trade. Half is the typical number, not a wall. Ask.

What happens if I miss a payment?

Call us before it's late. One honest phone call solves most problems. There's a 10-day grace period; after that, a late charge of 10% of that month's payment applies.

Will paying on time build my credit?

Not through us — we don't currently report in-house loans to the credit bureaus. If rebuilding credit is the goal, a credit union loan is the better tool, and we'll run every application past outside lenders first for exactly that reason.

One application covers both.

Apply once. If a lender approves you, great. If not, you'll hear what in-house looks like within a business day.